The minister announcing the money used a line you rarely hear from a government that has just opened a new gambling market: if you don’t gamble today, you absolutely should not start tomorrow. Dale Nally, Alberta’s Minister of Service Alberta and Red Tape Reduction, said it while confirming a CA$2.4 million (about US$1.7 million) grant to Brick House Recovery Centre to expand gambling treatment and recovery services across the province.
The timing is the interesting part. Alberta’s regulated iGaming market went live on July 13, and the treatment money arrived in the market’s first months rather than years later, once the harm statistics had piled up. That sequencing, plus the mechanism behind it, is what makes Alberta’s approach to responsible gambling funding worth a closer look than a single press release usually deserves.
Where does Alberta’s responsible gambling funding actually come from?
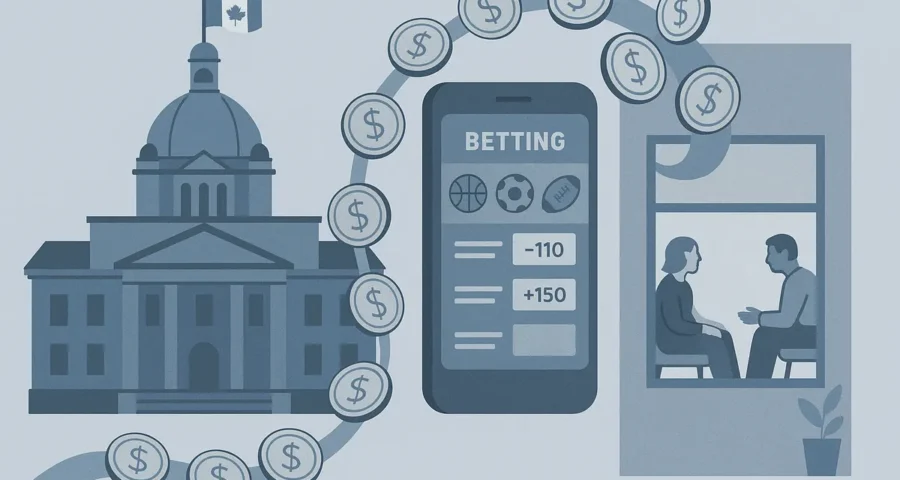
Operators. Under Alberta’s new iGaming regime, 1% of gross gaming revenue is directed to social responsibility programs covering education, research and treatment. The CA$2.4 million to Brick House is the first visible spend from that pot, and Nally has been explicit about who foots the bill: Albertans were already gambling, the province argues, so the point of regulation is to put player safety first and make the operator pay for the consequences.
Two design choices matter here. First, the levy is a percentage of revenue rather than a flat fee, so the money available for harm prevention grows as the market grows. Second, it is ring-fenced for social responsibility rather than dropped into general revenue, which makes it harder for treatment budgets to quietly lose an argument with road repairs at the next fiscal update.
There is a reasonable criticism of the model, and it should be stated plainly: a 1% levy ties the harm-prevention budget to gambling losses. If the market shrinks because fewer people are losing money, so does the funding. Jurisdictions that prefer stable, needs-based budgets tend to flag exactly that.
What does CA$2.4 million buy in problem gambling treatment?
Something concrete, which is refreshing. Brick House says the funding will support a publicly funded, flexible, person-centred outpatient program: four weeks of treatment followed by up to eight weeks of individualised aftercare. Services will be delivered in Edmonton and Calgary, with virtual treatment available province-wide so that geography isn’t the thing that stops someone asking for help.
Rick Wilson, Minister of Mental Health and Addiction, framed it around outcomes rather than throughput, pointing to recovery-focused supports that help people restore stability and work toward long-term recovery. The practical detail to note is the aftercare tail. Relapse risk in gambling disorder doesn’t end when a four-week program does, and funding the twelve-week arc rather than the intake is a meaningful distinction in treatment design.
Brick House isn’t the end of it. Alberta ran an open competition earlier in the year for organisations delivering coordinated outpatient and online gambling treatment and recovery services. Brick House is the first recipient; additional recipients were slated for selection late in the fall. So the CA$2.4 million is a first tranche through a competitive process, not the whole programme, and the eventual portfolio is expected to stretch across treatment, education and research.
How does a regulator balance market growth with player protection?
Not by choosing one. Alberta’s structure splits the jobs: the Alberta iGaming Corporation (AiGC) stands as the conduit for the commercial market, with 33 licensed sites accepting wagers in the market’s early months, while the social responsibility levy and the provincial health system handle the downstream harm. Commercial growth and harm minimisation sit on separate ledgers, funded by the same revenue.
For operators, the sequence is familiar from other regulated markets: get registered, accept the standards, pay the levy, and keep paying it as a condition of staying in the market. Player protection measures in a modern regime generally include age and identity verification, deposit and loss limits, self-exclusion, visible access to help services, and advertising rules that restrict targeting vulnerable groups. What Alberta adds on top is the funding obligation, which converts responsible gambling from a compliance checkbox into a line item that scales with revenue.
The honest framing for anyone writing or reading about this: these measures reduce harm at the margins. They do not change the underlying mathematics. Every regulated casino game carries a house edge, and over enough rounds the operator wins. Regulation decides who pays for the damage when that math meets someone who can’t stop.
Do other jurisdictions make operators pay for gambling harm prevention?
Increasingly, yes, but the mechanisms differ enough to matter. The three models below show the main options: a ring-fenced percentage of revenue, a statutory levy set centrally by sector, and a flat per-licensee fee.
| Jurisdiction | Funding mechanism | Scales with market? | Who directs the spend |
|---|---|---|---|
| Alberta | 1% of gross gaming revenue ring-fenced for education, research and treatment | Yes | Province, via open competition for service providers |
| Ontario | Operator revenue share paid through iGaming Ontario; treatment largely funded via provincial health and addiction budgets | Indirectly | Province and health system bodies |
| United Kingdom | Statutory levy on licensees, set by sector as a share of gambling yield, replacing voluntary contributions | Yes | Government and Gambling Commission-directed bodies, with NHS involvement in treatment |
| New Jersey | Fixed annual payment from each internet gaming licensee into state compulsive gambling programs | No | State addiction services and funded nonprofits |
Ontario’s experience is the most useful comparison for Alberta, since both provinces moved from a monopoly model to a multi-operator one. Ontario’s registrar standards impose detailed responsible gambling obligations on operators, but the money that reaches treatment travels through the health system rather than a named percentage of gaming revenue. That makes the budget more stable and the link to gambling revenue less visible. Alberta chose visibility.
The UK moved in the other direction after years of relying on voluntary contributions that depended on which operators felt like donating. Replacing that with a statutory levy collected across licence categories removed the awkward spectacle of harm-prevention charities negotiating with the industry that caused the harm. Anyone citing current UK levy rates or projected annual totals should check them against the Gambling Commission, since the figures have been revised during implementation.
New Jersey’s flat-fee approach is the cautionary one. A fixed annual sum per internet gaming licensee was reasonable when the market was small; it does not grow as handle grows, which means the harm-prevention budget and the market can drift apart over a decade. Alberta’s percentage model avoids that problem by construction.
Does up-front treatment funding help the regulated iGaming market?
It helps in ways that are hard to put on a balance sheet and easy to lose if you skip them. A 1% levy is a predictable cost of doing business, and most licensed operators price it in without blinking. What they get back is political durability. Regulated markets that fail usually fail politically, not commercially, and the standard attack line is that the state legalised gambling and pocketed the money while harm went unaddressed. Alberta has pre-empted that argument with receipts.
There is also a channelisation argument. The whole case for a regulated iGaming market is that players move from offshore sites with no KYC, no deposit limits and no self-exclusion to licensed sites that have all three. Funded treatment and visible help services strengthen that case; without them, the licensed market’s main claim to superiority gets thin.
What nobody can tell you yet is whether it works. Alberta’s levy will be judged on measurable outcomes: how many Albertans enter treatment, how many complete the twelve-week arc, what the waiting times look like once demand catches up with the new capacity, and whether the research funded alongside treatment produces anything a regulator can act on. Those numbers won’t exist for a couple of years. When they do, the 1% model either becomes the template other provinces copy or a well-intentioned footnote.
For readers rather than regulators, the practical takeaway is smaller and more immediate. Deposit limits, loss limits, session reminders and self-exclusion are built into every licensed site in Alberta, they cost nothing to use, and they work better set in advance than in the middle of a bad night. If gambling has stopped being entertainment, provincial addiction services and the funded outpatient programs now exist precisely for that call. For background reading, see our coverage of Canadian iGaming regulation and how responsible gambling tools work in practice.
Leave a Reply